Michael stayed angry for nearly a year.
He was the child most attached to the house.
Richard had taught him to ride a bike in the driveway.
They built shelves in the garage together.
Michael’s height marks still climbed the pantry doorframe under layers of paint.
To him, the house was family history.
That feeling was real.
Then he turned it into entitlement.
One day he called and said:
“You know Dad wanted the house to stay in the family.”
I answered:
“Your father left the house to me.”
“He assumed you’d pass it down.”
“He never said that.”
“He didn’t have to.”
“Yes. He did.”
That sentence ended the conversation.
Richard and I had discussed the house only once in estate terms.
He said:
“If you ever want to sell, sell.”
That was all.
Michael had built a promise from nostalgia.
I invited him to meet Thomas with me, not to disclose my estate plan but to hear one legal fact clearly.
The house was mine.
I could live in it, sell it, mortgage it, renovate it, or leave it according to my lawful choices.
Michael refused the meeting.
Then he stopped calling.
I let him.
That was painful.
I had repaired things with Lisa and begun repairing with Jennifer.
Every family instinct told me to chase the remaining child.
I did not.
Six months later, Michael’s contracting business had a cash-flow crisis after a commercial client delayed payment.
He called.
“Mom, I need help.”
My heart reacted before my brain.
“How much?”
“Forty thousand.”
Old Maggie would have transferred it that day.
New Maggie asked:
“For what?”
“Payroll and suppliers.”
“Is this a loan or a gift?”
He became offended.
“Seriously?”
“Yes.”
“I’m your son.”
“Yes. That does not answer the question.”
I met with Elena and Thomas before deciding.
Not because they controlled my money.
Because I wanted objective advice.
I could afford to help.
Forty thousand was more than I wanted to risk.
I offered a twenty-five-thousand-dollar documented loan with a reasonable repayment schedule and no claim against his house.
Michael exploded.
“You have over a million dollars.”
“That is not the same as having unlimited money.”
“You’d rather let my business fail?”
“I offered twenty-five thousand.”
“With paperwork.”
“Yes.”
“You don’t trust me.”
“I trust written agreements.”
He hung up.
Two days later, he accepted.
We signed a promissory note.
He used the money for payroll and supplier balances.
The delayed client paid six weeks later.
Michael began repaying me monthly.
The first payment was exactly on time.
So was the second.
He paid the loan off eighteen months early.
At the final payment, he came to my house with a paper receipt he had made as a joke.
PAID IN FULL, MOM.
I laughed.
Then he said:
“I hated that you made me sign papers.”
“I know.”
“You were right.”
I waited.
“Not because I would have cheated you. Because it made me treat your money like money instead of Mom’s money.”
That was the sentence our relationship needed.
He did not apologize for everything that day.
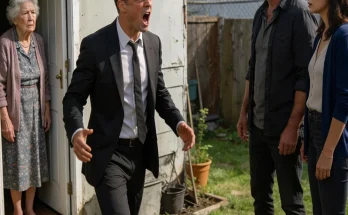
He apologized specifically for climbing the gate.
“That was ridiculous.”
“Yes.”
“I thought being your son meant I could force my way into a conversation.”
“Yes.”
“I know better.”
That was enough to start again.
The loan to Michael became a small family controversy after Jennifer learned about it.
“You gave him twenty-five thousand dollars?”
“I loaned it.”
“Why didn’t you tell us?”
“Because it was between Michael and me.”
“What if he never pays you back?”
“Then the agreement explains what happens.”
She wanted to review the paperwork.
I said no.
That was another boundary.
Fairness among adult children does not require identical treatment in every moment, especially when one child has a specific need and the parent makes an informed choice.
It does require me to consider whether I am creating hidden promises or future resentment.
Thomas suggested documenting the loan clearly so the estate would know whether any balance remained if I died.
That was practical, not punitive.
Michael appreciated the structure only later.
He told me the paperwork forced him to build repayment into his business cash flow instead of thinking, Mom will understand if I skip a month.
He never skipped.
That experience changed how he later handled loans with his own adult son.
He required paperwork too.
When his son complained, Michael said:
“Your grandmother taught me.”
I consider that one of my quieter victories.
Michael’s repayment schedule became a running joke because he sent payments with increasingly ridiculous memo lines.
LOAN PAYMENT, DEFINITELY NOT INHERITANCE.
MOM’S TERRIFYING PAPERWORK FUND.
GATE REPAIR PENANCE.
I saved screenshots.
Humor did not trivialize the old conflict. It showed we could refer to it without reopening the wound every time.
More importantly, Michael’s business became more disciplined after his cash-flow scare. He created a larger reserve and stopped relying so heavily on one client.
“Your loan saved us,” he once said.
“No. Your client paying and your business recovering saved you. The loan bought time.”
That distinction mattered.
I did not want him turning my help into another story where Mom always rescues him. He had done the work.
I had chosen a limited, structured form of support.
That was healthier for both of us.
Michael’s view of inheritance changed most visibly when one of his friends complained that his elderly mother was “spending everything on assisted living.”
Michael told me later that he almost agreed automatically.
Then he heard himself.
He answered:
“What else is her money for?”
I was proud of him.
Not because he adopted my opinion.
Because he had internalized the principle strongly enough to apply it when I was not in the room.
Real change is what people do when the person who taught the lesson is absent.
Michael’s documented loan also protected his siblings. If I had simply handed him twenty-five thousand dollars and died shortly afterward, Jennifer or Lisa might have interpreted it as favoritism or an advance on inheritance.
Because the transaction was clear, there was nothing to guess.
Good records do not mean a family lacks trust. Sometimes they preserve trust by preventing memory from becoming evidence.
Michael later borrowed a much smaller amount from me for a truck repair and surprised me by bringing the promissory note himself.
“You trained me,” he said.
I laughed.
The loan was repaid in three months.
By then, paperwork no longer meant distrust to him. It meant clarity. That change made financial help less emotionally dangerous for both of us.
Michael’s best change was simpler. He stopped saying, “But I’m your son,” whenever a boundary frustrated him. Family identity remained important. It stopped functioning as a master key.
Michael kept the final loan receipt in his office for years. He said it reminded him that help and responsibility can exist together. I liked that. Support did not have to mean rescue, and paperwork did not have to mean distrust.
Michael later told me the gate was the first time he realized I could say no to him as an adult and mean it. I wished he had learned that lesson more gently. He probably did too. At least he learned it.
One more thing mattered in this part of the story: progress was never one dramatic decision. It came from small choices repeated until they became normal. That pattern, more than any document or argument, was what changed our family over time.
Click here to continue reading: PART 7: Once My Children Stopped Treating My Money as Their Future, We Could Finally Talk About My Aging Without Every Conversation Sounding Like an Estate Meeting
The Day My Children Told Me to “Figure It Out Yourself,” I Stopped Begging for Their Attention and Started Protecting My Own Future
Part 6 of 16